A promise to limit building regulation changes and BNG requirements is not the shot in the arm which the industry needs, writes Eleanor Jolliffe
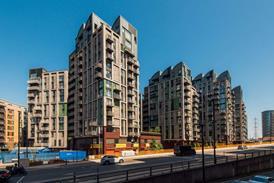
This summer was very hot. In my flat it was possibly even hotter as access to my balcony was removed to allow cladding remedial work to be carried out on the building. Sadly I fell victim to the Ardmore Construction Group collapse and work ground to a halt a few months ago. Now, following a very hot summer with no balcony I look set to endure a winter with no insulation while the building management scrambles to find a new contractor to take over the building work. It has been deeply frustrating, not to say uncomfortable.
I write this, partly to garner sympathy, but also to introduce the more serious note - perhaps no one who reads Building Design will consider this news as such - but construction is in a perilous position at the moment. My personal pain is mirrored across the country in stalled, paused and scaled down construction projects. Turbulence from Brexit, Covid, the Building Safety Act, Russia’s war with Ukraine, the Iran conflict and the resulting turmoil in the Middle East have all contributed to disrupting supply chains, limiting the availability of skilled labour, disrupting financial markets, raising construction prices and restricting the availability of funding. Architectural services, of course, are existentially tied to this and more than one practice has folded or made people redundant this year.
Government figures suggest that construction output has fallen by around 1% in the three months to August 2026, with the private new-build residential sector falling by 3.2%. While longer term data shows construction holding fairly level, global circumstances don’t suggest a sudden boom in UK construction. Indeed Gardiner and Theobald’s latest market report suggest that while the volume of opportunities in the pipeline is slowly improving the likelihood of projects progressing has deteriorated. Contractors are more selective about what they will bid for, price validity periods are shortening on their tenders and capacity pressure on key trade packages such as MEP, structural steel and drylining is limiting the market.
Perhaps their caution is warranted though, 16% of all corporate insolvencies in the 12 months to September 2026 were construction companies (just less than 4,000 in total), a 20% increase on the 12 months to (pre-Covid) 2019. When figures are broken down by type of construction activity more categories recorded an increase in insolvencies this year than a decrease. Architectural and engineering activities sits in a different category but accounted for context for around 17% of all insolvencies in the professional, scientific and technical activities category (335 in total) and 1.4% of overall insolvencies, (compared to 14% and 1% in 2019). The numbers themselves are smaller, but there are about five times fewer architectural and engineering firms than construction companies so you would expect that - but the trends paint a similarly worrying picture.
It is not just companies going under. EY-Parthenon data shows that housebuilders have issued more profit warnings in 2026 than at the peak of the 2008 global financial crisis. Taylor Wimpey have pulled out of the London housing market and Berkeley has not purchased new land in the capital for the last four years, both citing viability pressures. BD reported this week that Stephen Teagle, partnerships chief executive at Vistry, cited the “cumulative regulatory burden” as the most challenging cost pressure facing the housebuilder at the moment and Paul Rickard, chief executive of housebuilder Pocket Living, added “combined impact of historic and recent regulations and taxes on the housing sector” to “regulatory layering” as the biggest pressure on margins. British Land has paused new development work at its large Canada Water site… I could go on
On the services side Oliver Milton, managing partner at Hawkins\Brown has cited people as a cost pressure on practices with salaries struggling to keep pace with inflation while recruitment, retention and other employment costs have increased, compounded by fixed fees which make it difficult to pass increasing costs on to clients.
But this is perhaps not news to any of us.
I filed this column a day late - waiting to see if the chancellor of the exchequer would offer hope or recognition of the structural issues with the construction market. I am no financial expert but I don’t think limiting building regulation changes and BNG requirements was the shot in the arm that was needed. The new First Home scheme to replace Help to Buy might help secure buyers for volume housebuilders but as far as I know no building commitment has been extracted from housebuilders to secure this support. There’s nothing that seeks to increase domestic manufacturing capacity, nothing that directly addresses the root causes of high energy costs, nothing that looks set to mitigate the skills crisis, all as unemployment rises to 5%. Apparently I will get £100 towards my electricity bill… though with no one to replace the insulation on the walls that won’t go far!

No comments yet